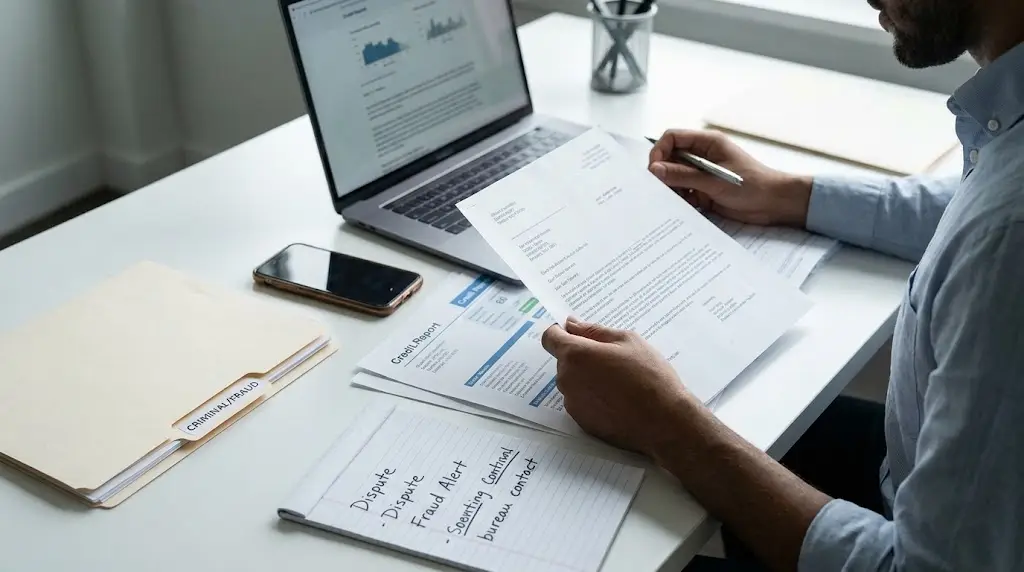
An identity theft credit report dispute is not just a paperwork issue. It is a time-sensitive financial control process. A fraudulent collection account, unfamiliar credit card, or false address can affect lending decisions, raise borrowing costs, and delay a home purchase or business funding application. The priority is to contain the exposure, create a clean record of the facts, and track every response until the file is accurate.
For professionals and business owners, speed matters. But speed without organization can create avoidable gaps. A disciplined process helps protect your personal credit profile while preserving the financial readiness behind your next move.
Start by Securing the Credit File
Before sending dispute letters, reduce the chance of additional fraudulent activity. Request and review reports from all three nationwide credit bureaus. Identity theft does not always appear on every report, and the same fraudulent account may be reported differently across bureaus.
Look beyond unfamiliar balances. Review names, addresses, employers, hard inquiries, authorized users, collection accounts, and public-record information. An address you do not recognize may indicate that someone used your identity to open accounts elsewhere. A hard inquiry can be an early sign of an attempted application, even if no account was ultimately opened.
Place a fraud alert or a security freeze based on your needs. A fraud alert asks lenders to take additional steps to verify identity before extending new credit. A security freeze generally restricts access to your credit report for new applications until you lift it. A freeze provides stronger preventive control, while a fraud alert may be more convenient if you expect to apply for financing soon. The right choice depends on your immediate plans and the level of risk.
If you believe the theft is ongoing, contact affected lenders directly. Ask them to close fraudulent accounts, stop new charges, and provide their fraud documentation process. Keep a record of every call, including the date, representative name, case number, and next required action.
Build an Identity Theft Evidence File
A well-supported dispute is easier to review and easier to manage. Create one organized file for every document, confirmation number, and communication. Do not rely on a scattered email inbox or verbal assurances from a creditor.
Your file should generally include:
- Copies of government-issued identification and proof of your current address
- Credit report pages with fraudulent information clearly identified
- A Federal Trade Commission identity theft report, if applicable
- Statements or letters from creditors showing unauthorized activity
- Copies of correspondence, dispute submissions, and delivery confirmations
- A contact log that tracks deadlines, outcomes, and follow-up dates
The Federal Trade Commission identity theft report can be particularly useful when requesting an identity theft block. Under the Fair Credit Reporting Act, a credit bureau may be required to block information resulting from identity theft within four business days after receiving a qualifying identity theft report, proof of identity, and the required information identifying the fraudulent accounts or transactions.
That does not mean every item disappears automatically. The bureau may ask for additional information or determine that the request does not meet the legal requirements. Strong documentation and precise account identification make the process more efficient.
How to File an Identity Theft Credit Report Dispute
File a separate dispute with each credit bureau reporting the inaccurate information. Describe the issue clearly: identify the creditor, account number, date opened if known, and the specific reason the item is fraudulent. Avoid broad statements such as “this is not mine” without context. State that the account resulted from identity theft and attach the records that support your claim.
A dispute should be factual, focused, and complete. Include copies, not originals, of supporting documents. Retain the originals in your evidence file. If submitting by mail, use a method that provides proof of delivery. If submitting electronically, save confirmation pages and upload receipts.
You may also dispute directly with the company furnishing the information, such as the bank, lender, or collection agency. This is often a productive parallel step because the furnisher controls its own account records and may be able to correct or close the account before the credit reporting process is complete.
Be careful not to dispute accurate negative information simply because it is inconvenient. A legitimate late payment, collection account, or high balance requires a different strategy. Identity theft disputes should remain precise and credible. Mixing valid concerns with unsupported claims can slow resolution and make progress harder to track.
Use Clear Language and Specific Requests
Your request should identify what you want the bureau or creditor to do. Depending on the facts, that may include blocking the fraudulent account, deleting an inaccurate inquiry, correcting personal information, or stopping collection activity on a debt created by identity theft.
Keep the tone professional. The goal is not to argue. The goal is to provide enough information for the reviewer to verify the error and take action. If an investigation returns an incomplete or inaccurate result, respond with the missing documentation and explain exactly what remains unresolved.
Track Investigation Deadlines and Results
Credit bureaus generally investigate disputes within 30 days. That period can extend in certain situations, including when additional information is provided during the investigation. The bureau should provide the results and an updated report if changes are made.
Do not treat a response as final without reviewing it. Compare the updated report against your original dispute and supporting records. Confirm that the account, balance, status, inquiries, and personal information are all corrected as needed. An account may be marked closed but still remain associated with you, or a balance may be updated without the fraudulent history being removed.
Maintain a simple tracking system with the submission date, bureau or creditor, account involved, documents sent, investigation deadline, response date, and outcome. This is where organized progress creates an advantage. You can see what has been resolved, what needs escalation, and whether the same inaccurate item continues to appear across multiple reports.
If a bureau verifies information you believe is fraudulent, request the method of verification and review the response carefully. You can submit additional evidence, dispute with the furnisher directly, add a statement to your report in some cases, or consider speaking with a consumer protection attorney when the financial damage is significant or the reporting continues after clear proof has been provided.
Protect Your Financing Plans While the Dispute Is Open
An unresolved fraudulent account can complicate a mortgage, auto loan, business credit application, or refinance. If you expect to seek financing soon, document the active dispute and preserve all related correspondence. A lender may need context for an account or inquiry that is still visible while the investigation is underway.
At the same time, keep the rest of your credit profile stable. Make all legitimate payments on time, avoid unnecessary new applications, and monitor utilization on existing revolving accounts. Identity theft recovery is more manageable when the valid parts of your credit file continue to show consistent, responsible behavior.
For entrepreneurs, personal credit protection also supports business momentum. Many early-stage funding decisions still consider the owner’s personal financial profile. Resolving fraudulent activity promptly can help prevent an identity theft event from affecting vendor terms, equipment financing, or access to working capital.
When Structured Support Makes Sense
Some cases are straightforward: one fraudulent account, clear documentation, and a timely correction. Others involve multiple creditors, collection agencies, mixed files, repeated reinsertions, or an urgent financing deadline. In those situations, a structured support system can reduce confusion and keep the process moving.
Calloway Credit helps clients organize credit-improvement work into a clear, trackable path, so documentation, progress, and next steps do not get lost across disconnected tasks. The objective is not just to respond to a credit report error. It is to restore a profile that supports stronger financial options.
Identity theft can create pressure, but it does not require a disorganized response. Protect the file, document the facts, follow each deadline, and verify every result. That steady process puts you back in control of the credit decisions ahead.